Three different tools give three different numbers. Here is what each one is for and when to trust it.
“How much is my house worth?” is one of the most searched real estate questions there is, and it has at least three different answers depending on which tool you ask. An automated online estimate, a comparative market analysis from an agent, and a licensed appraisal are built for different purposes, and treating one like the others is where sellers run into trouble.
Automated Estimates: A Starting Point, Not a Price
Tools like Zillow's Zestimate pull from public records and recent sales to generate an instant number. They are a reasonable starting point for curiosity, but not for pricing. Zillow's own data shows a median error rate of 1.9% for homes currently on the market, but that error rate jumps to 7.5% for homes that are not listed, since the algorithm has less current data to work with. These tools cannot see inside your home, so renovations, deferred maintenance, and lot quality generally are not factored in. Use an automated estimate to satisfy curiosity. Do not use it to set a list price.
The Comparative Market Analysis: What Agents Use to Price a Home
A comparative market analysis, or CMA, is prepared by a real estate agent using three to six recently sold properties similar to yours in size, age, condition, and location, with adjustments made for the differences between them. A well prepared CMA typically lands within 2 to 4% of the eventual sale price. On a $400,000 home, that is roughly an $8,000 to $16,000 range, tight enough to set a defensible list price without leaving money on the table or scaring off buyers with an unrealistic number. This is the tool worth requesting before you list.
The Appraisal: The Number That Determines Financing
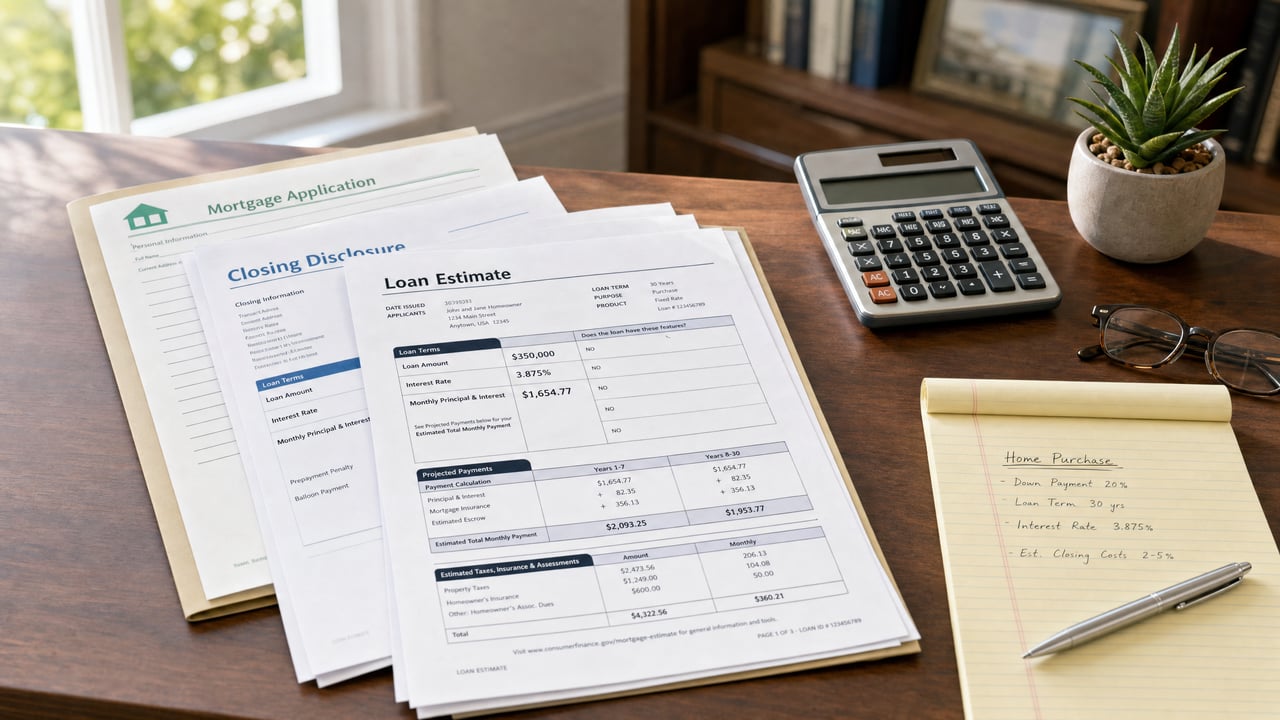
An appraisal is a formal, in person valuation performed by a licensed appraiser, and it is required by the buyer's lender before a mortgage can close. Unlike a CMA, which is prepared to help set a list price, an appraisal exists to protect the lender by confirming the home supports the loan amount. A standard single family appraisal costs $300 to $500, while multi family or luxury properties can run $500 to $800. Because the buyer's lender orders it, sellers do not choose who performs it or influence the outcome.
When the Numbers Do Not Match
It is common for these three numbers to differ, and a gap between them is not automatically a problem. If an appraisal comes in below the contract price, the buyer, seller, and agents typically have a few options: renegotiate the price, have the buyer cover the difference in cash, or contest the appraisal with additional comparable sales. Knowing this ahead of time keeps a low appraisal from feeling like a crisis instead of a normal part of the process.
Getting the Most Out of a CMA
A CMA is only as good as the comparables behind it, so come prepared. List out any renovations, upgrades, or major repairs you have made, along with rough dates and costs, since these do not show up automatically in public records. Ask your agent to walk you through why each comparable was chosen and what adjustments were made for differences in size, condition, or lot. If your home has an unusual feature, a large lot, an accessory dwelling, an outdated system, ask specifically how that was accounted for. A good agent welcomes these questions, since a defensible price protects both of you once the home is on the market.
Common Pricing Mistakes Tied to These Numbers
Anchoring your expectations to a Zestimate and feeling shortchanged when a professional CMA comes in lower or higher.
Waiving an appraisal contingency in a competitive offer without understanding you would be responsible for covering any gap in cash.
Treating a CMA prepared six months ago as still accurate; local comparables shift, and pricing conversations should use recent, current data.
Assuming a high appraisal means you could have listed higher; appraisals support financing, they are not a substitute for market based pricing.
Value Also Matters If You Are Not Selling
Home value is not only a selling question. Lenders lean on similar valuation methods when you apply for a home equity line of credit, a cash out refinance, or removal of private mortgage insurance once you have built enough equity. If you are exploring any of those options rather than a sale, a fresh CMA or a lender ordered appraisal is still the more reliable starting point than an automated estimate, for the same reasons outlined above.
Which Number Should You Trust
Use an automated estimate for a rough sense of value out of curiosity. Use a CMA from a local agent when you are getting ready to list, since it accounts for your home's condition and current local comparables in a way an algorithm cannot. Treat the appraisal as the number that matters most once you are under contract, since it is the one that determines whether financing goes through.
Ready to Talk Through Your Options?
Buying or selling always comes down to your specific goals, timeline, and finances, not just the headlines. If you would like to talk through what any of this means for your situation, reach out to Black Tie Realty. We are happy to answer questions, walk through the numbers, and help you build a plan, no pressure attached.
Black Tie Realty | blacktierealtyne.com
Sources
Zillow Zestimate Accuracy (2026): The Honest Truth — https://houwzer.com/blog/the-zillow-zestimate-can-it-be-trusted/
Comparative Market Analysis (CMA): An In-Depth Guide — https://listwithclever.com/real-estate-blog/comparative-market-analysis-real-estate/
How to Accurately Estimate Your Home's Value — Opendoor — https://www.opendoor.com/articles/how-to-accurately-estimate-your-homes-value
The Truth About Appraisals vs. Zestimates — KW Appraisal Group — https://kwappraisalgroup.com/appraisals-vs-zestimates/